All Categories
Featured
Comparing the Best 2026 Medicare Advantage Options

Top-Rated IUL Policies for Secure Retirement Planning
Understanding PPO and HMO Health Insurance
If the insured passes away within this two-year period, the recipient will receive all premiums paid plus interest. The premiums for VALife are repaired and based on your age when you enroll. When locked in, your premiums will not increase. For more details on premium costs, please visit. There are no premium waivers for the VALife program. You will require to submit your very first premium payment when you apply. Leaving military service indicates leaving behind Servicemembers 'Group Life Insurance Coverage (SGLI)and finding out what comes next can be complicated. Veterans typically have more than one course to protection, and the right one depends on your health, your budget plan, and what you're trying to safeguard. This guide strolls through the primary options VGLI, VALife, and private life insurance so you can understand how they work before deciding what to do next.( Household SGLI) optional coverage service members can add for a partner and reliant kids. (Traumatic Injury Protection )short-term financial support after a serious terrible injury.(Veterans' Group Life Insurance )group term coverage available once you've separated from service, covered in detail below.(Veterans Affairs Life Insurance coverage)guaranteed-acceptance entire life insurance for veterans with a service-connected disability, also covered below. S-DVI stopped accepting brand-new applications after December 31, 2022; VALife is now the program for new applicants because category. If you already hold an S-DVI policy, has existing, policy-specific information. This guide focuses on the two options most veterans compare after leaving service VGLI and VALife together with where private life insurance coverage suits. VA normally provides you a limited window to transfer to other coverage, and the specific details depend upon your particular transition retirement, separation, or moving to the Reserve or National Guard, amongst others. The most typical next step is applying for VGLI, which is created specifically to select up where SGLI leaves off but real deadlines use, which is why it's worth checking out the VGLI area listed below before deciding what to do.
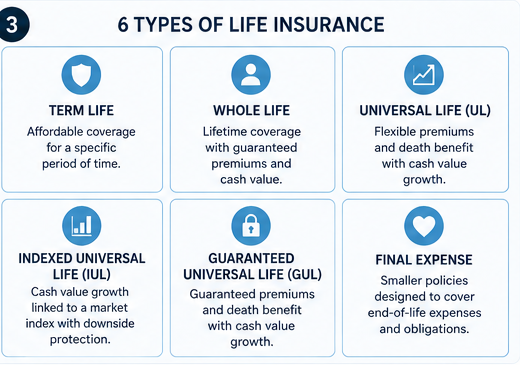
VGLI(Veterans 'Group Life Insurance Coverage )is group term life insurance coverage offered to eligible veterans and former service members after they leave the military. It's created as an extension of SGLI, not a separate program you need to certify for from scratch. typically, veterans who had SGLI while serving and are applying within the eligibility window after separating, retiring from the Ready Reserve or National Guard, or a few associated situations. VGLI offers term coverage from $10,000 as much as$500,000. Your initial coverage quantity is typically based on the SGLI protection you had while serving, and you can use to increase it gradually as much as the$ 500,000 optimum. VGLI premiums are based on your age and how much coverage you pick they typically increase as you age. this is the part most worth taking note of. You generally require to use within 1 year and 120 days of leaving service. Within the first 240 days of that window, you can enroll without responding to health questions or taking a medical exam. After 240 days however still within the overall due date VA will inquire about your health when you use. Particular veterans age 81 or older may also qualify under specific VA guidelines for example, if they looked for VA impairment compensation before turning 81 but didn't get their rating decision up until after.
Insurance in West Covina CASince eligibility has specific conditions, confirm your precise eligibility on instead of presuming based upon age alone. VALife is entire life insurance, meaning it's permanent coverage( not term )that can develop money worth with time, and premiums are fixed based upon your age when you register they do not increase later because of age or health changes. S-DVI stopped accepting brand-new applicationsafter December 31, 2022, and VALife is its replacement program. Here's how the 2 programs compare, side by side. Neither is generally much better they're constructed for different circumstances. Veterans/former service members who had SGLI, applying within the eligibility window after separationVeterans age 80 or younger with a qualifying service-connected impairmentrating (specific veterans 81+may also certify)$10,000 to$500,000 Approximately $40,000, in $10,000 incrementsNoneFull stated value normally starts after 2 years of paid premiums; earlier death generally returns premiums paid plus interest VA is specific that veterans can get personal life insurance coverage at any time, separate from VGLI or VALife. See VA's guidance onpersonal insurance. Private insurance coverage isn't instantly much better or even worse than VA protection it's a different set of tradeoffs. Personal policies typically involve medical underwriting( health questions, in some cases a test), and prices and eligibility vary by insurance provider. Some veterans find personal coverage costs less than they expect if they're in great health; others find VA's guaranteed-acceptance or no-health-review choices more important particularly due to the fact that those concerns do not use to them. Yes. VA is explicit on this point: you can look for both VGLI and a personal life insurance policy they're not equally special. This can make sense if you want more overall coverage than VGLI alone supplies, or if you just want to compare youroptions side by side before dedicating. If you're doing this, timing matters. See the "Veterans With Health Issues"area listed below it's particularly about protecting your VGLI eligibility while you're also checking out personal protection. For a deeper side-by-side look at how VGLI and private protection compare including when each might make more sense see our complete contrast: VGLI vs. There's no single formula that fits everybody, and basic general rules(like"10 times your income" )can be a reasonable starting point but frequently miss what actuallymatters for your scenario. A few of the elements worth analyzing: how much of your earnings would your household require changed, and for for how long? balances that would still need to be paid if you weren't there to pay them. if you're wanting to assist fund a kid's education. funeral, burial, and relatedcosts. SGLI, VGLI, VALife, company coverage, or savings you currently have that would offset what's required elsewhere. what your household might realistically make use of, including any survivor benefits. Weighing all of this by hand is a lot. For a more detailed take a look at these elements and how they fit together, see How Much Life Insurance Coverage Do I Need?. If your primary concern is last expenditures specifically funeral and burial costs rather than earnings replacement LifeCoverPath's is developed around that instead. If you have a health condition, timing your VGLI application matters more than almost anything else in this guide. For more on weighing VGLI versus private protection without risking your VGLI timing, see VGLI vs. Private Life Insurance coverage: What Veterans Ought To Know.

Latest Posts

Comparing 2026 Medicare Part D Enrollment
Comparing the Best 2026 Medicare Advantage Options

Medicare Part D Coverage Tips for 2026